17, October 2025
The Regulatory Storm Has Passed: Where Is the Next Big Opportunity in PMGD?
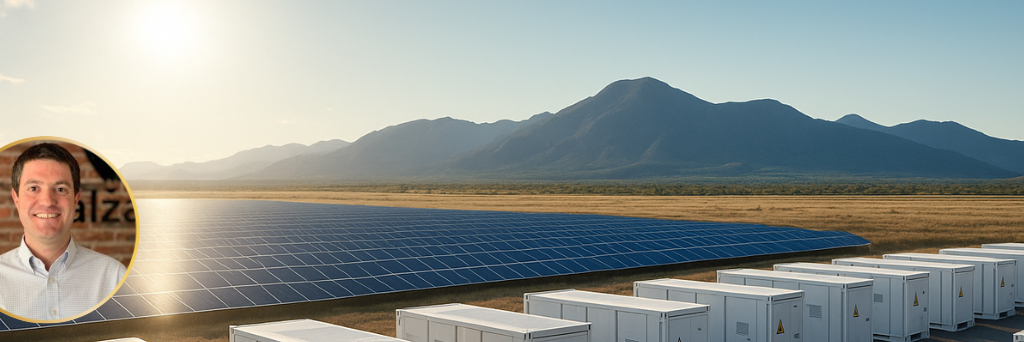
Chile’s Small Distributed Generation Systems (PMGD) industry, which has grown exponentially to exceed 3 GW of installed capacity, has been a resounding success. However, its evolution has been marked by intense regulatory volatility. Following the implementation of Decree 88 and the debates surrounding compensation mechanisms, many investors adopted a cautious stance. The good news is that the main uncertainty — the one that threatened the core revenue model — has already materialized and consolidated. We are now at a turning point where relative stability opens the door to a new wave of more sophisticated and profitable investments: hybridization with Battery Energy Storage Systems (BESS).
The market’s main concern has been the change in the stabilized pricing regime, moving from the pre-DS88 model (which did not internalize zero spot prices) to a system based on six hourly blocks. For photovoltaic projects — which account for more than 83% of the sector — this change posed a direct threat to profitability, as it forced them to sell energy primarily during the lowest-priced hours. However, this change is now law and has already been absorbed by the market. The current uncertainty is no longer about whether prices will change, but rather about how the system will manage them.
Today’s business opportunity no longer lies in replicating the old model, but in solving the problems created by PMGD’s own success.
Congestion and Arbitrage as the New Standard
The two main technical challenges in the PMGD market — congestion in the distribution grid and high exposure to zero marginal prices during midday solar oversupply — have stopped being problems and have instead become the new risk premium and the new business opportunity.
Congestion Mitigation: Grid congestion limits the plants’ injection capacity, resulting in lost revenue. A BESS system allows the plant to store generated energy and discharge it into the grid when congestion is lower, ensuring the asset can utilize its full nominal capacity. This reduces curtailment risk (zero dispatch) and stabilizes cash flow.
Price Arbitrage: The DS88 six-hour block framework, which penalizes daytime injection, is precisely the mechanism that maximizes battery value. Financiers should view BESS not as a capital expenditure burden, but as a revenue enabler. Batteries allow for temporal price arbitrage — buying at low prices (during the day) and selling at high prices (during evening peak hours) — which can potentially double project revenues in the Chilean market.
Financing Is Focused on Flexibility
For financiers — banks, private debt funds, and private equity firms — the hybrid PMGD plant (Solar + BESS) represents a far more attractive risk proposition than a standalone solar plant.
Battery integration transforms an intermittent asset into a dispatchable one. This substantially improves the project’s credit quality for three key technical reasons:
Cash Flow Protection: By enabling arbitrage and congestion mitigation, batteries make free cash flow (FCF) projections significantly more robust and predictable, mitigating market risk.
Improved Debt Service Coverage Ratio (DSCR): Revenue optimization increases the DSCR, the key metric used to assess a project’s ability to service its debt. A higher DSCR translates into lower lender risk.
Valuation of Ancillary Services: BESS not only injects energy into the grid, but also provides ancillary services (such as frequency and voltage control), which are increasingly valued and compensated by the National Electric Coordinator. This creates an additional revenue stream.
The era of blind bets on stabilized pricing is over. Today, the real margin lies in financing the capital expenditure (Capex) required for energy storage. Chile, with its ambitious target of 6 GW of storage capacity by 2050, not only needs it, but the current regulatory framework — although strict — has already laid the foundation for BESS to become a profitable necessity. Financiers who invest in flexibility and the dispatchable capacity of hybrid projects will be the true winners in the consolidation of the PMGD industry.
Álvaro Alliende W.
Partner